International expansion is no longer limited to large corporations with dedicated treasury departments. Small and medium-sized enterprises are increasingly working with overseas suppliers, selling products to international customers, and hiring professionals across different countries. While these opportunities create new sources of revenue, they also introduce financial challenges that businesses operating exclusively in domestic markets rarely encounter.
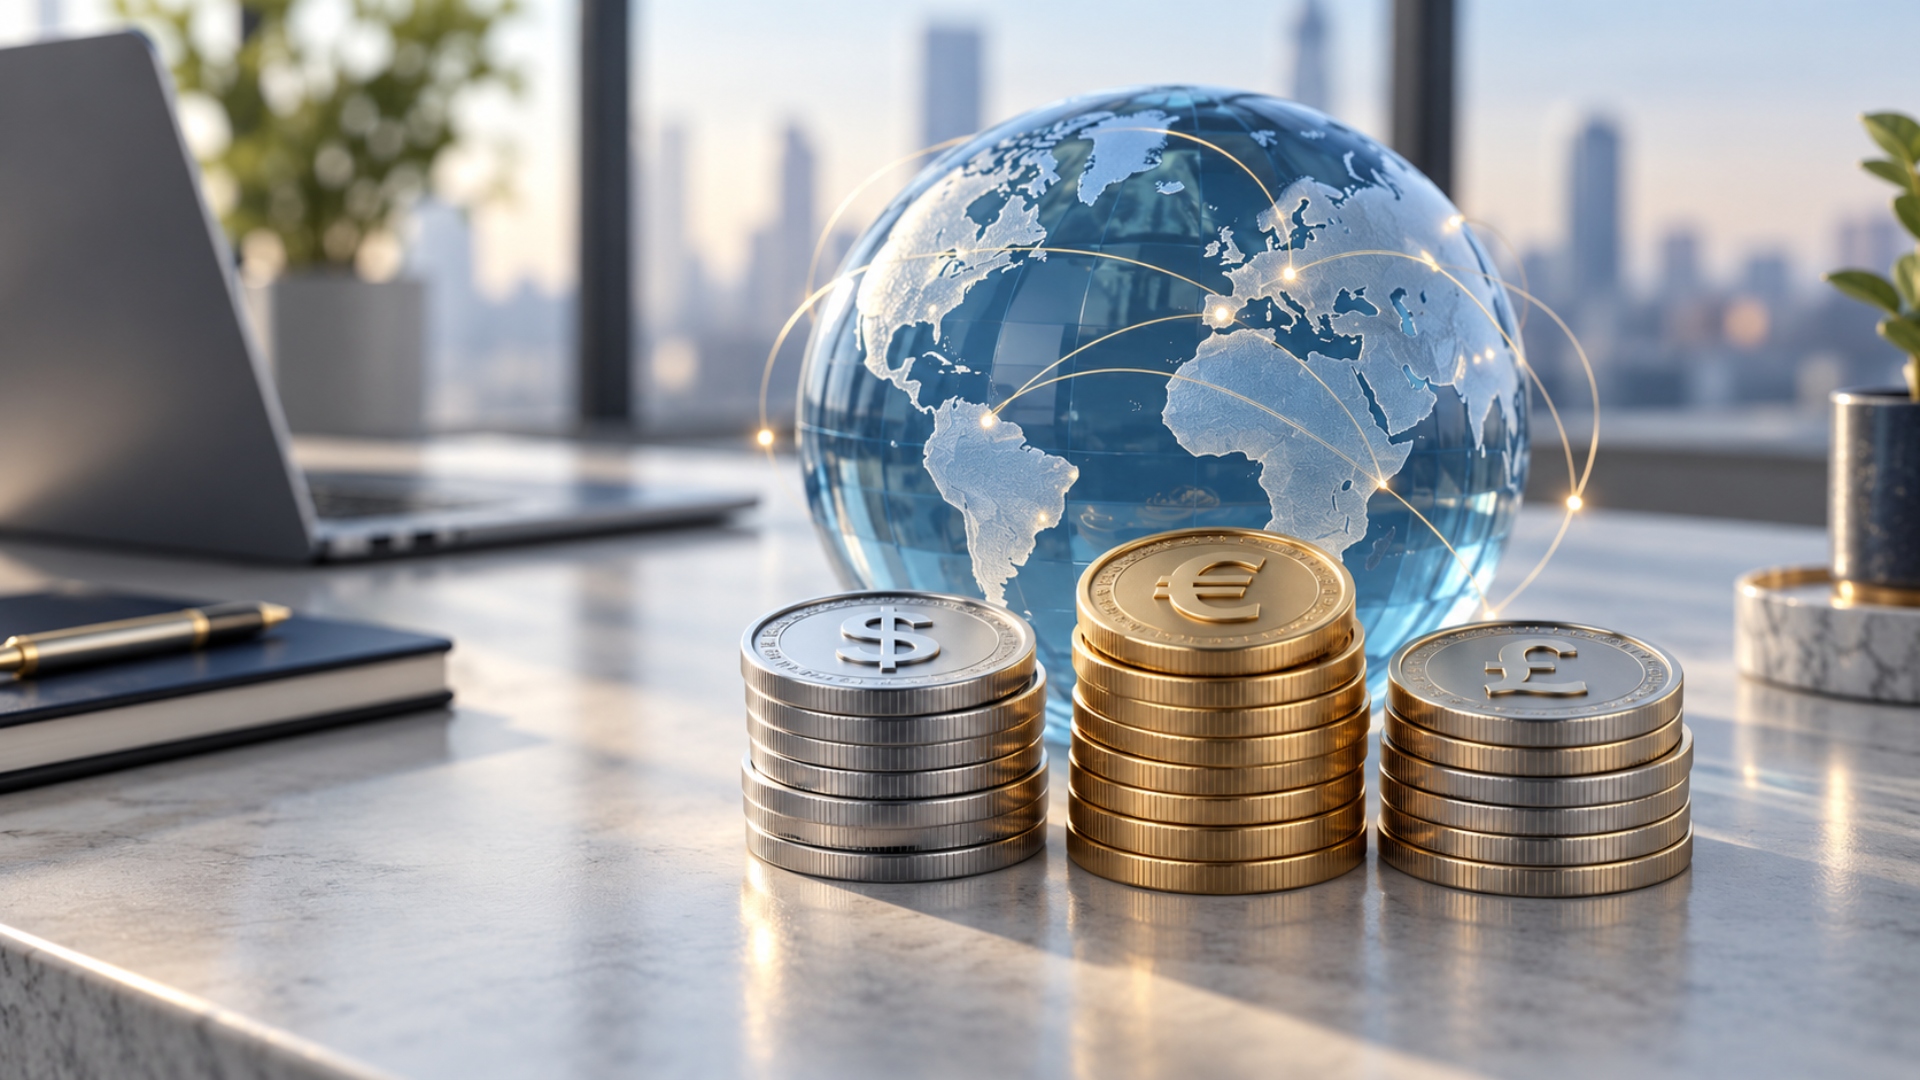
One of the most significant challenges is managing payments in different currencies. As international transactions become more frequent, businesses must consider exchange rate fluctuations, payment processing costs, and the timing of incoming and outgoing funds. Financial tools such as a multi currency account can help companies organise balances in different currencies and reduce the need for unnecessary conversions when their payment arrangements support this functionality.
However, effective currency management involves more than choosing the right financial account. It requires a broader understanding of cash flow, operational risks, and the financial implications of international growth.
The Financial Challenges of Operating Across Borders
Expanding into international markets creates opportunities for businesses to diversify their customer base and establish relationships with new suppliers.
However, dealing with multiple currencies introduces additional complexity into daily financial operations.
Consider a European company that receives payments from American customers in US dollars but pays its employees and domestic suppliers in euros. If the business immediately converts every incoming payment, it may incur foreign exchange charges even when some of those dollars could have been used to pay international suppliers.
Repeated conversions can gradually increase operational costs.
Exchange rate movements also influence profitability. A company agreeing to pay an overseas supplier a fixed amount in a foreign currency may discover that the cost has increased by the time the invoice becomes due.
For businesses operating with narrow profit margins, even relatively modest exchange rate changes can affect financial performance.
International payments may also involve additional processing fees, intermediary institutions, and different settlement times.
These factors make it essential for companies to evaluate the full cost of cross-border transactions rather than focusing exclusively on advertised transfer fees.
Why Cash Flow Visibility Matters
Cash flow management becomes more complicated when a company receives income and makes payments in several currencies.
A business may appear financially healthy when reviewing total account balances, yet still face short-term difficulties if sufficient funds are unavailable in the currency required for an upcoming payment.
For example, an international e-commerce company might receive revenue in euros and pounds while paying manufacturers in US dollars.
Although its overall cash position may be positive, the business must still determine when and how to convert funds to meet its obligations.
Without accurate forecasting, companies may be forced to exchange currencies at inconvenient times or face unexpected payment delays.
A structured approach to cash flow management can help address these challenges.
Businesses should maintain clear records of incoming payments, outstanding invoices, planned expenses, and the currencies associated with each transaction.
Forecasting these movements over several weeks or months allows financial teams to identify potential funding gaps before they become urgent.
Centralised reporting can also improve decision-making by providing a clearer view of the company’s international financial position.
Rather than evaluating each payment in isolation, businesses can understand how individual transactions contribute to overall liquidity requirements.
Reducing Unnecessary Currency Conversion Costs
Currency conversion is an unavoidable part of many international business activities, but not every transaction needs to involve an immediate exchange.
Companies that regularly receive and spend the same foreign currency may benefit from holding part of their operational funds in that currency, provided their account arrangements allow it.
For instance, a marketing agency with clients in the United States may receive dollar-denominated payments while also paying American software providers and contractors.
Using those incoming dollars for eligible expenses could reduce the number of conversions required.
Nevertheless, holding foreign currencies is not without risk.
Exchange rates can move in either direction, and businesses holding balances in foreign currencies remain exposed to fluctuations in their value relative to the company’s reporting currency.
The objective should therefore be to align currency balances with expected operational needs rather than attempting to predict short-term market movements.
Businesses should also compare exchange rates and fees carefully.
An international payment may involve a visible transaction charge, a margin included in the exchange rate, or additional fees charged by intermediary institutions.
Understanding these costs is essential when comparing financial service providers and estimating the true cost of international operations.
The Growing Role of Financial Technology
Financial technology has changed how businesses access payment services and manage international transactions.
Digital financial platforms increasingly offer online account management, transaction monitoring, and tools for organising payments across different markets.
These capabilities can be particularly valuable for smaller businesses without extensive internal finance teams.
Instead of relying entirely on manual processes, companies can use digital tools to monitor balances, review transaction histories, and improve the accuracy of financial reporting.
Some providers also support integration with accounting or enterprise management systems, helping businesses reduce repetitive administrative work.
However, financial technology solutions should be evaluated according to operational requirements rather than the number of features advertised.
Companies should examine supported currencies, available payment networks, transaction limits, settlement arrangements, and customer support.
Security and regulatory status are equally important.
For example, electronic money institutions and traditional banks may operate under different regulatory frameworks, including differences in how customer funds are protected.
Business owners should understand the legal nature of the services they use, how funds are safeguarded, and whether the provider supports transactions in their intended markets.
Choosing a payment solution is ultimately a financial management decision rather than simply a technology purchase.
Building a More Resilient International Payment Strategy
As a business grows internationally, currency management should become part of its wider financial planning.
The first step is understanding the company’s exposure to different currencies.
Financial teams should identify which currencies generate the most revenue, which are used for major expenses, and how frequently conversions are required.
The next consideration is payment timing.
International transactions may take different amounts of time to settle depending on the destination, payment network, and institutions involved.
Maintaining sufficient liquidity for upcoming expenses helps reduce disruption caused by unexpected delays.
Businesses should also establish internal procedures for authorising transactions, reviewing exchange costs, and reconciling international payments.
Clear responsibilities and appropriate access controls can reduce administrative mistakes and support stronger financial oversight.
For companies with significant currency exposure, additional risk management measures may be appropriate.
These can include negotiating invoice currencies with suppliers, matching foreign-currency income with expenses, or considering suitable hedging arrangements through qualified providers.
The most appropriate approach depends on transaction volumes, available resources, and the company’s tolerance for financial risk.
Regular reviews are essential because the requirements of a growing business can change quickly.
A payment arrangement that works well for occasional international transactions may become inefficient once the company begins operating across several markets.
Conclusion
International growth creates valuable opportunities for businesses, but it also requires more sophisticated financial management.
Currency fluctuations, transaction costs, and settlement delays can influence cash flow and profitability, particularly for smaller companies with limited financial resources.
Developing a structured approach to currency management helps businesses understand these risks and make more informed decisions about international payments.
Digital financial services can support this process by improving visibility and simplifying certain operational tasks, but they work best when combined with sound financial planning and clear internal controls.
As cross-border commerce becomes a routine part of business activity, effective currency management is increasingly an essential component of sustainable international growth.