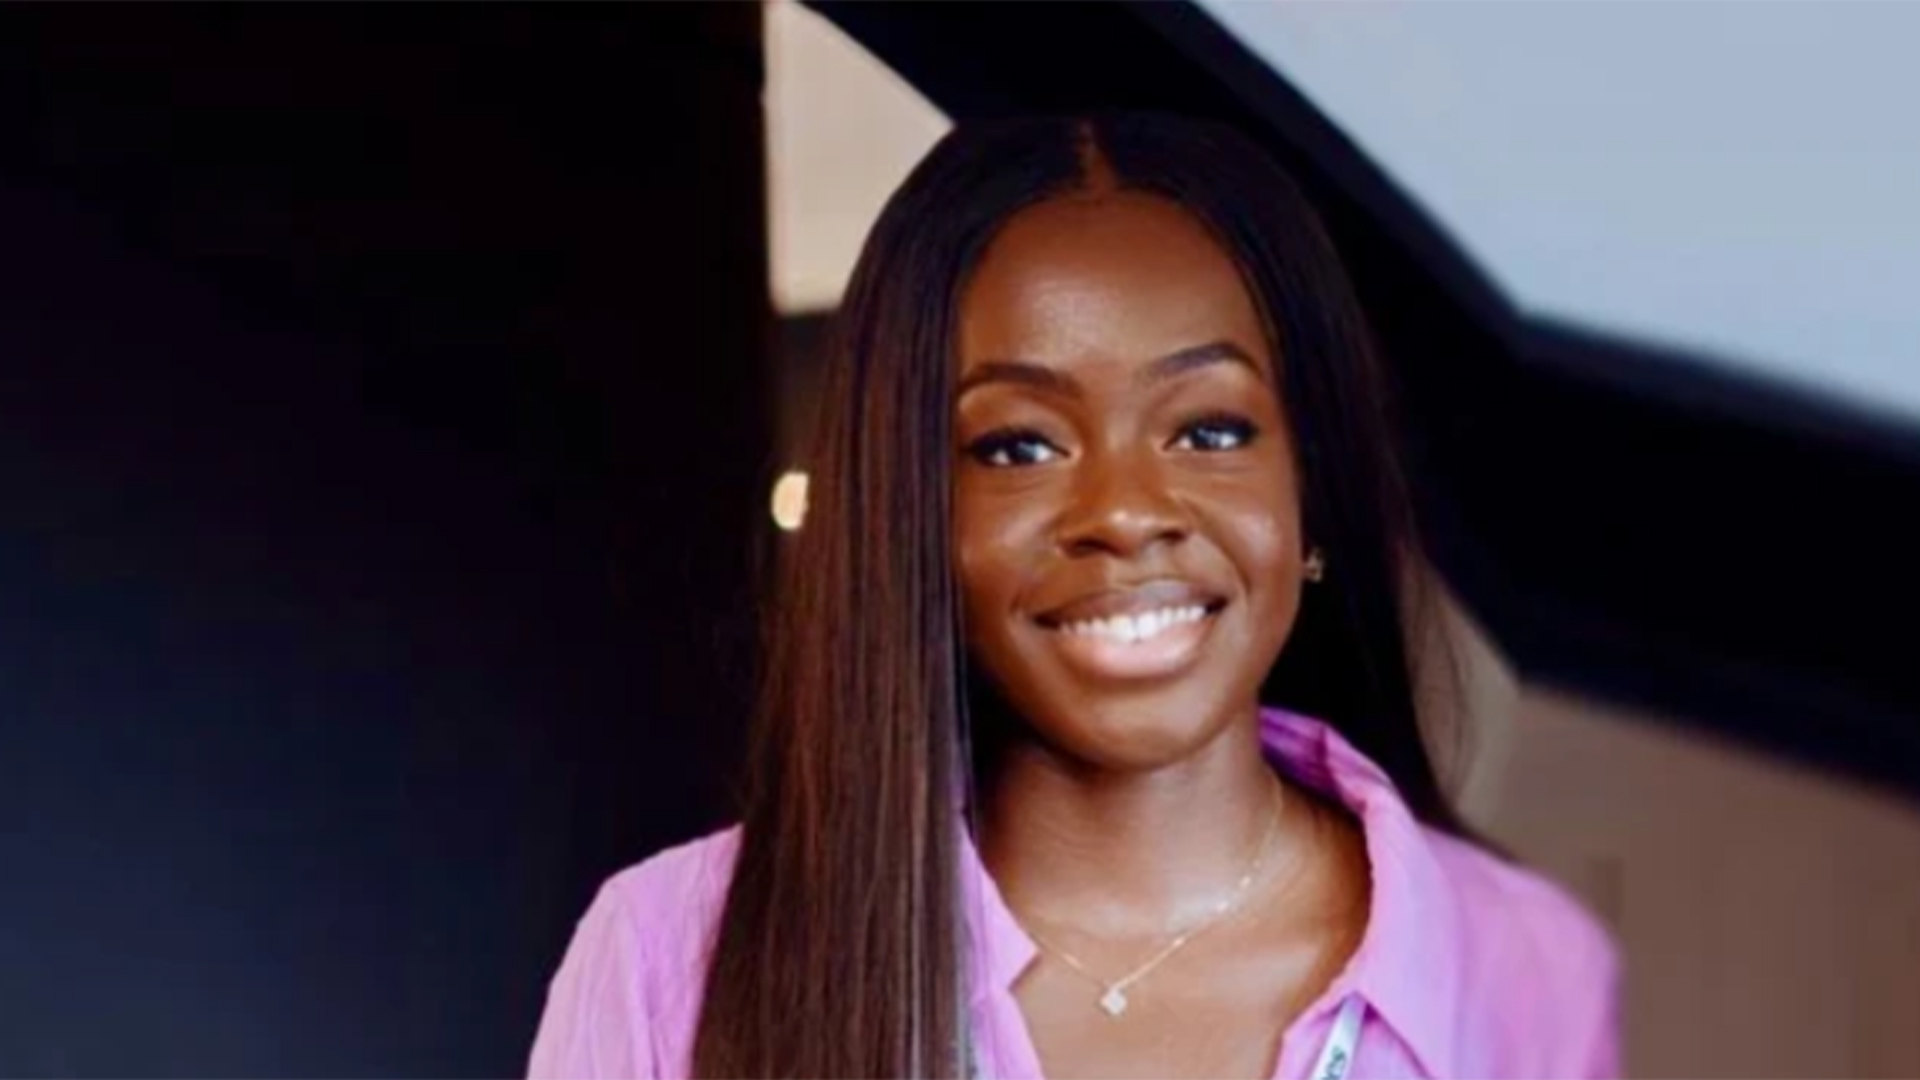
This exclusive interview with Tomi Popoola was conducted by Tabish Ali of the Motivational Speakers Agency.
Tomi Popoola sits at the intersection of finance, cloud infrastructure and artificial intelligence, where the investment case for AI is increasingly being tested against hard measures such as cost, risk and margin.
The founder and CEO of Slash Finances, Popoola previously worked as a Solutions Architect at AWS and began her career at JP Morgan.
Her background spans computer science, finance, fintech and large-scale cloud systems, giving her a close view of how financial institutions are trying to turn AI from an experiment into an operating advantage.
In this interview with the AI Speakers Agency, Popoola examines the metrics investors should watch to judge whether AI is creating measurable value, where automation can genuinely expand margins in financial services, and the risks that could weaken the investment case, from model opacity and regulatory pressure to rising infrastructure and governance costs.
1. Which metrics best reveal whether AI investment is delivering measurable financial and operational returns?
Tomi Popoola: “The most revealing metrics are those where machine intelligence should produce outcomes that humans or rules-based systems simply cannot match at scale.
“Fraud loss rate is often the cleanest signal of model effectiveness. Look for sustained reductions without a corresponding spike in false positives that reject legitimate transactions.
“Cost-to-serve per account captures the operational impact of automation across support, compliance, and underwriting. If AI is working, this number should fall without a degradation in service quality.
“Credit approval rates alongside default metrics are particularly instructive together. Rising approvals paired with stable or declining charge-offs suggest better risk discrimination, not just looser standards.
“CAC to LTV ratios can improve meaningfully if AI enables more precise targeting, better product-market fit at the customer level, and higher cross-sell conversion.
“Manual review rates are perhaps the most underused metric. The proportion of transactions still requiring human intervention in fraud, compliance, or underwriting is a direct measure of automation effectiveness. Consistent declines here translate almost mechanically into margin expansion.”
2. Where can AI create genuine margin expansion in financial services, and where are the costs simply being redistributed?
Tomi Popoola: “The distinction matters, because not all AI investment produces real gains, as some of it just moves costs around.
“Genuine expansion is clearest in fraud prevention, where better models directly reduce losses and chargeback expenses while lowering the volume of manual investigations.
“Customer support automation is another real opportunity: AI systems can resolve a substantial share of routine inquiries such as balance queries, dispute handling, and account management, reducing the fixed cost base of call-centre infrastructure. In credit underwriting, more accurate risk models can increase approval rates while holding loss rates steady, effectively improving revenue per customer without proportionally increasing risk.
“The cost-transfer category is less discussed but equally important. Model governance and compliance infrastructure, including documentation, explainability frameworks, and ongoing monitoring, remains an unavoidable overhead regardless of how good the underlying models are. Inference costs can also become material at scale, particularly for real-time fraud systems processing millions of transactions. Model risk management adds a persistent operational layer, requiring continuous testing for bias, drift, and regulatory compliance.
“The businesses best positioned to capture net margin improvement are those with high transaction volumes, such as payment networks, digital lenders, and large fintech platforms, where even incremental improvements in accuracy or efficiency scale into economically significant gains.”
3. What risks could undermine the investment case for AI across fintech and financial services?
Tomi Popoola: “The most underappreciated risk sits at the intersection of model opacity and regulatory expectation. Financial services demand accountability and explainability, particularly in lending and fraud decisions, and yet many high-performance AI models are inherently difficult to interpret.
“If regulators decide certain approaches aren’t transparent enough, institutions could face restrictions on automated decisions, expensive new oversight requirements, or pressure to fall back on simpler, less capable systems. The compliance cost could quietly cancel out many of the efficiency gains that justified the investment in the first place.
“Three warning signs are worth watching. AI-enabled fraud escalation is easy to underestimate. Criminal networks are increasingly sophisticated, and if they come to use AI more effectively than financial institutions can defend against it, fraud losses could rise sharply and quickly across payment networks and digital platforms.
“Regulatory intervention remains a live risk, particularly around bias in automated lending decisions and consumer protection. Restrictions in these areas could slow deployment in ways that are hard to predict in advance.
“Finally, rising costs could quietly erode the investment case. If spending on infrastructure, model management, and governance grows faster than the efficiency gains it produces, margins deteriorate rather than expand.
“The financial AI thesis ultimately depends on a cost curve that keeps improving, and any meaningful reversal of that should be taken seriously.”